 Learn hubBlog
See where the seven DYOR options indicators live, which question each one answers, how Binance and Deribit differ, and where else options appear on the platform.
You do not have to trade options to watch them. They show what those who trade them expect. DYOR has seven options indicators. Each answers one question.
| Indicator | Question |
|---|---|
| OPTIONS OI | How many rights are open now: calls and puts? |
| OPTIONS PUT/CALL | Which are there more of: puts or calls? |
| OPTIONS VOLUME | How many options were traded in this bar? |
| OPTIONS IV | How expensive are options, that is, how big a move is expected? |
| OPTIONS SKEW | Which is more expensive: insurance against a fall or a bet on a rise? |
| OPTIONS MAX PAIN | At what price would option buyers receive the least? |
| OPTIONS GEX | How many forced trades will a price move cause? |
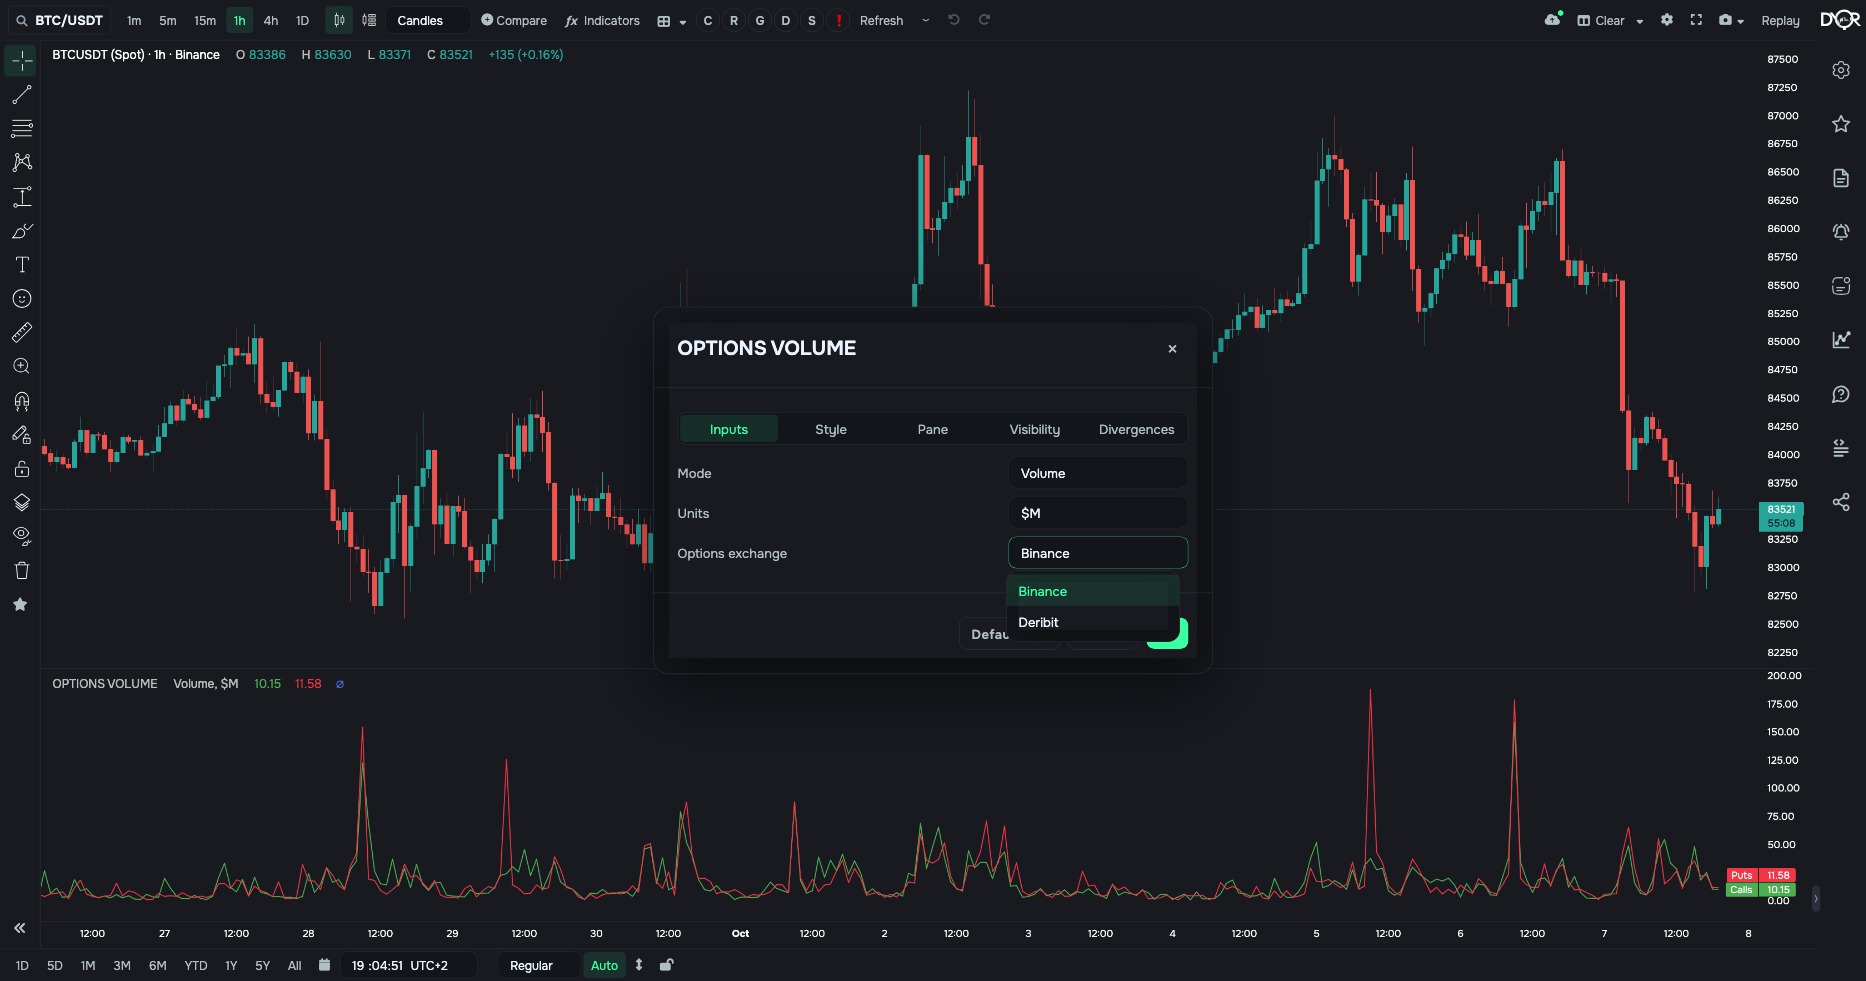
| Binance | Deribit | |
|---|---|---|
| Assets | BTC, ETH, BNB, SOL, XRP, DOGE, gold, silver | BTC, ETH, SOL, XRP, HYPE, AVAX, TRX |
| Volatility index | BVOL, history since June 2023 | DVOL, history since 2021 |
| BTC options OI on 1 October 2026 | $1.6 bn | $30.8 bn |
| Word | What it means |
|---|---|
| At the money (ATM) | A strike near the current price: an 86,000 call with the price at 86,000. Out of the money — the right is useless for now: a 90,000 call or an 80,000 put with the price at 86,000. In the money — the right is already worth something: an 80,000 call with the price at 86,000 lets you buy 6,000 below the market. |
| Notional | The value of the asset the options are written on: coins × price. A call on 1 BTC with the price at 86,000 has a notional of 86,000, although 1,000 was paid for it. Ten such calls — a notional of 860,000. |
| Premium | How much was paid for the options themselves. |
| Delta | By how many dollars the premium changes if BTC moves by 1 dollar. A 90,000 call with the price at 86,000: delta 0.28, a 1,000 rise in BTC gives about 280. An at-the-money call: about 0.5, a 1,000 rise gives about 500. A call deep in the money: about 1, it moves almost like the coin. Puts have a negative delta: a put gets more expensive on a fall. A second reading: delta 0.28 is roughly a 28% chance that the option ends up in the money at expiry. |
| 25Δ | A call and a put with roughly a one-in-four chance of paying off: the call above the price, the put below. Why it is measured by chance and not by distance: a strike “5% from the price” is far away in a calm market and close in a stormy one, while “one in four” is the same in any market. With the price at 86,000 that is roughly a 92,000 call and an 81,000 put. OPTIONS SKEW compares the price of such a put and such a call. |
| Gamma | How fast delta itself changes as the price moves. |
| Block trade | A large trade agreed directly, bypassing the order book. |
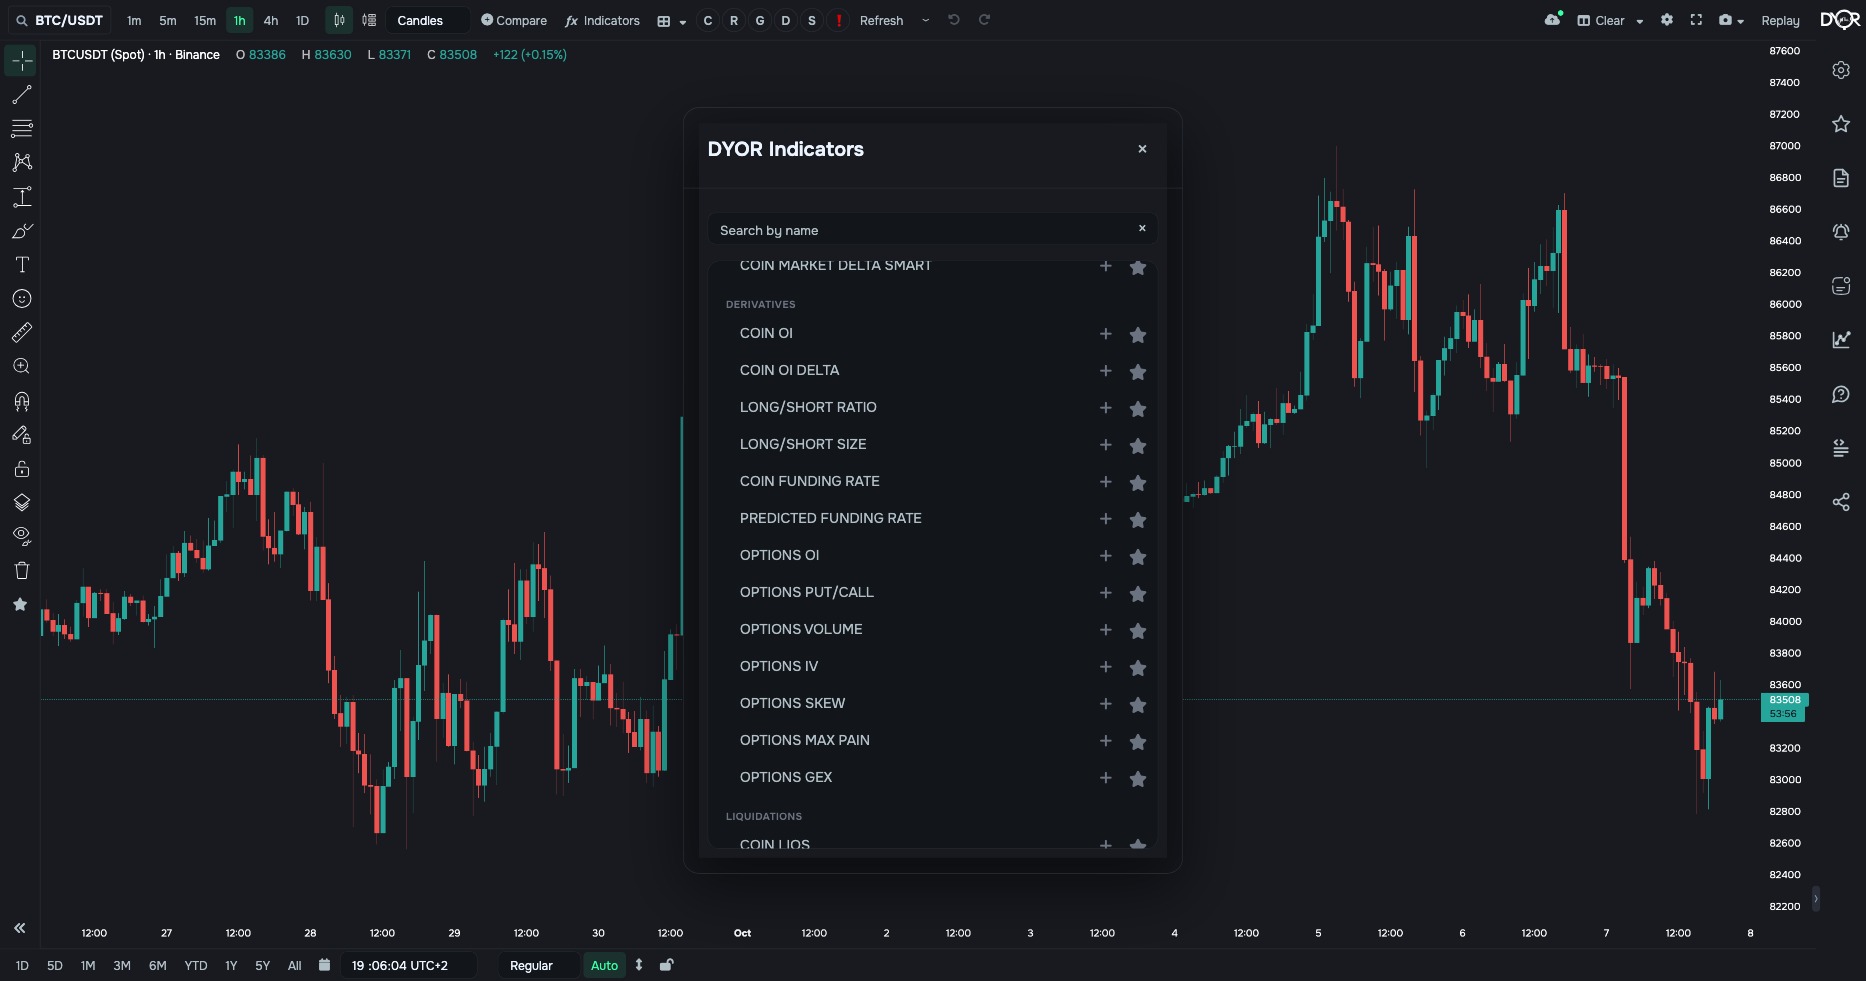
The seven OPTIONS indicators live in the COIN › Derivatives group; the “Options exchange” field picks the exchange. Data accumulates from 30 September 2026. The same numbers are available in alerts and in the Metrics Builder.
Where do the DYOR options indicators live?
Correct answer: Indicators › COIN › Derivatives, with OPTIONS in the name