 Learn hubBlog
Take apart OPTIONS SKEW — which is more expensive: insurance against a fall or a bet on a rise.
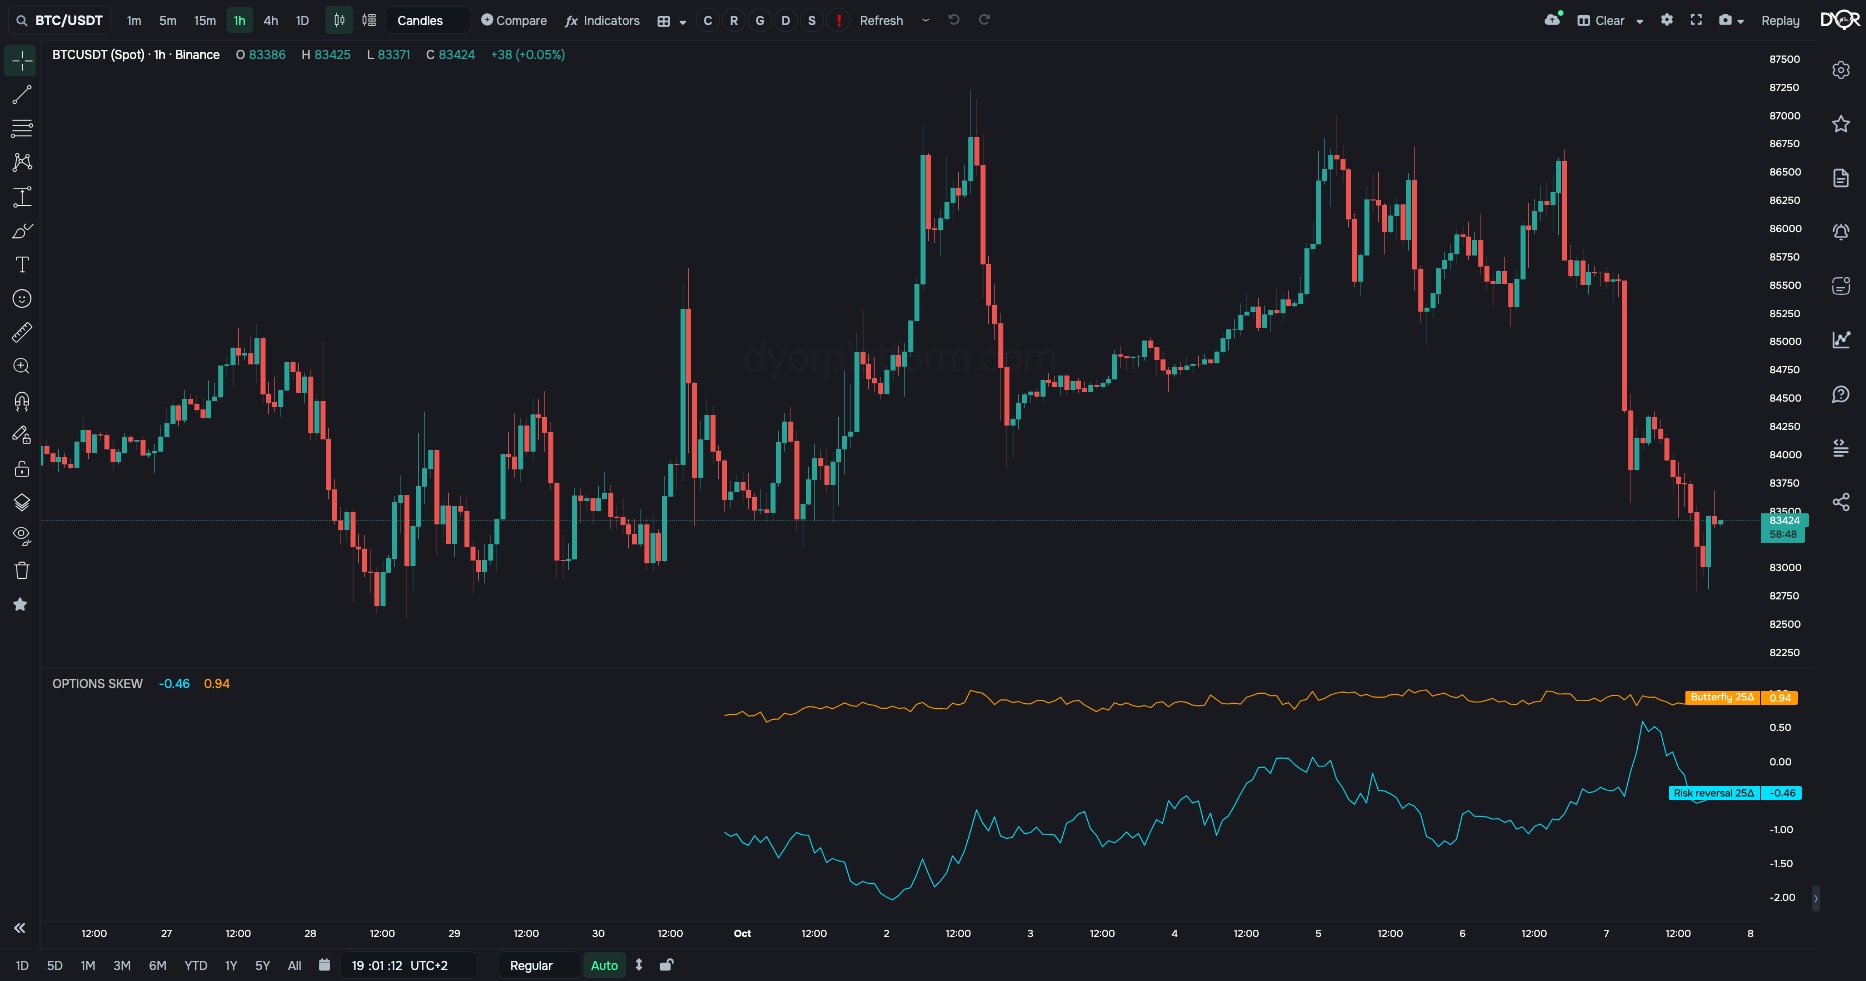
Which is more expensive: insurance against a fall or a bet on a rise.
Starting simple. Take two options at the same distance from the price: a put below the price and a call above it. The put is insurance against a fall. The call is a bet on a rise.
“More expensive” is measured in IV from the OPTIONS IV lesson. The options’ term is 30 days. There are two lines on the chart.
An example with Binance numbers for 1 October 2026.
| 30-day option | What it is | IV |
|---|---|---|
| 25Δ put | insurance against a fall | 35.67 |
| At the money | strike at the current price | 34.02 |
| 25Δ call | a bet on a rise | 33.99 |
What 25Δ is. It is a way to pick “the same distance from the price”. Options are taken whose chance of paying off is, roughly, one in four. Both values are in volatility points.
Deribit on the same day: risk reversal −1.65, butterfly 0.71. Puts are 1.7 points more expensive than calls: more is paid for protection against a fall than for a bet on a rise.
See what is paid for more: insurance against a fall or a bet on a rise.
For example.
| Field | Options | Default | What it changes |
|---|---|---|---|
| Exchange | Chart | Chart | Cannot be switched for options indicators: there are no other values in the list. The options exchange is chosen by the “Options exchange” field below. |
| Options exchange | Binance Deribit | Binance | Whose options to count. The chart’s exchange does not affect this: the indicator takes only the coin from the chart. - Want Binance options — Binance. - Want the main options exchange, with 19 times more BTC open interest — Deribit. |
In the Style two lines: Risk reversal 25Δ and Butterfly 25Δ.
Metric OPTIONS. Condition fields:
“Options exchange” — Binance or Deribit. “Options metric” for this indicator: 25Δ Risk Reversal 30D and 25Δ Butterfly 30D. The “Exchange” and “Market type” fields are in the form, but the options asset is taken from the coin.
The 25Δ risk reversal is the call’s IV minus the put’s IV: below zero puts are more expensive. The 25Δ butterfly is how much more expensive the wings are than the middle. Both lines are in volatility points, 30-day term.
25Δ risk reversal = −1.68. What does it mean?
Correct answer: Puts are 1.68 volatility points more expensive than calls